Making an Offer on a House in Ontario: A Buyer's Guide
You've found the house. The neighbourhood is right, the layout works, and you can already picture where the couch goes. Now comes the part that trips up even well-prepared buyers: turning that feeling into a signed deal before someone else does.
Making an offer on a house in Ontario involves more paperwork, deadlines and legal commitments than most buyers expect. In Milton and the West GTA, this is the stage where homes are won or lost, often before buyers realize what happened.
I've spent over a decade negotiating offers in this market. This guide covers what I walk every buyer through: the forms, how deposits work, the conditions that protect you, the irrevocable period and the tactics that get offers accepted.
What's in the Agreement of Purchase and Sale
The moment a seller signs your offer, you have a legally binding contract. It's not a letter of intent or a handshake. Both you and the seller are legally committed to closing.
In Ontario, most offers use the OREA Form 100 for freehold homes or Form 101 for condos. You aren't legally required to use those forms. A lawyer-drafted agreement works too, as long as it includes the required elements.
What every valid offer must include
A valid offer needs the purchase price, the legal land description of the property (not just the street address), the closing and possession date, the deposit amount and when it's due, and a clear list of the fixtures and chattels included.
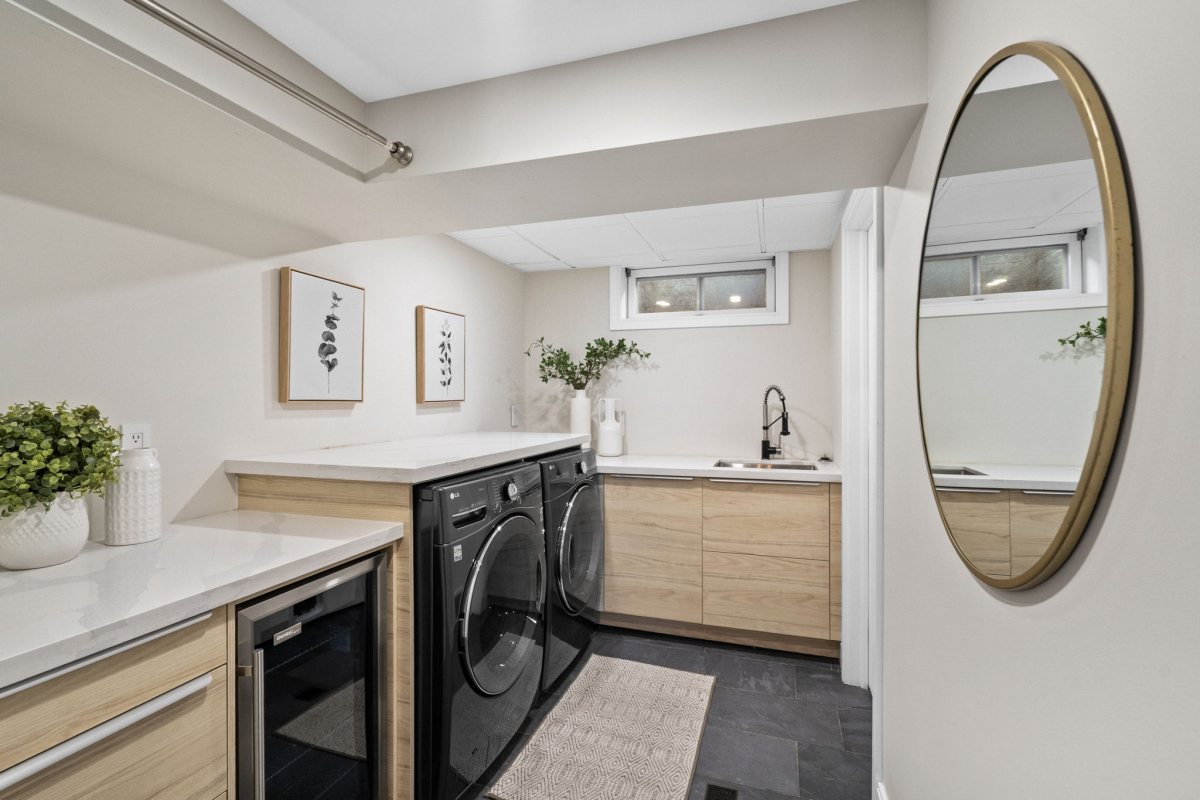
Fixtures are permanently attached, like light fixtures and built-in shelving. Chattels are movable, like the fridge, stove, washer and dryer. If a chattel isn't written into the offer, it isn't included.
The agreement should also list any rental items, such as a hot water tank or alarm system, because you take over those contracts at closing. HST needs to be addressed in writing too. Resale homes are usually exempt, but it still belongs in the agreement so there's no dispute later.
Firm vs. conditional offers
A firm offer has no conditions. Once the seller signs, the deal is done. A conditional offer gives you a set window to confirm things like financing or a home inspection before the deal becomes binding. If a condition isn't met, you can walk away and get your deposit back.
In a competitive market, firm offers carry more weight. But the strongest offer isn't always the smartest one. Waiving conditions without the right preparation exposes you to real legal and financial risk. My goal is to make your conditions tight and credible, not to strip away protection you need.
How Deposits Work in Ontario
The deposit is one of the most misunderstood parts of an offer. Buyers mix it up with the down payment, worry about where the money goes, or underestimate how much it tells the seller about how serious they are.
How much to put down and when
In Milton and the GTA, deposits usually run 3% to 5% of the purchase price. On a $900,000 home, that's $27,000 to $45,000. The deposit is generally due within 24 hours of acceptance, by bank draft or certified cheque. Personal cheques aren't accepted.
Deposits can also be structured in two stages, or timed around holidays, when a situation calls for it. I'll tell you what makes sense for your offer.
A larger deposit is also a competitive tool. It shows the seller you're financially ready and committed, which can tip the balance when two offers are close in price.
Where your deposit goes and what protects it
Your deposit goes into the listing brokerage's trust account. It never goes to the seller or an agent directly, and that account is regulated under TRESA, the Trust in Real Estate Services Act. RECO's deposit insurance covers up to $200,000 per claim if a brokerage commits fraud, misuses funds or goes insolvent, with no deductible and no cost to you.
When the deal closes, your deposit goes toward your down payment. If a condition isn't met, it's returned in full. If you back out after your conditions are removed, the seller can pursue the deposit, and the money can't be released without both parties agreeing or a court order.
The Conditions That Protect You
Conditions protect buyers. The three most common in Ontario are financing, home inspection and, for condos, the status certificate review. Each one gives you a set window to check something before you're fully committed.
Financing and home inspection
A financing condition, usually 5 to 10 business days, protects you if your mortgage approval falls through or the appraisal comes in below your price. The clause should say the financing must be satisfactory to you "in your sole and absolute discretion." That wording lets you walk away if the terms don't work for you, not only if you're turned down.
A home inspection condition, usually 5 to 7 business days, lets you bring in a qualified inspector and renegotiate or walk away if serious problems turn up. In Milton's current market, a 10-day window can make sellers nervous. Three to five days shows you're organized and still keeps you protected.
Status certificate review for condo buyers
If you're buying a condo, never skip the status certificate review. It shows the reserve fund balance, any upcoming special assessments, legal disputes involving the corporation, monthly fees and the building's rules. It can run over 100 pages, and you usually get 5 to 7 business days to review it.
Have a lawyer read it. They know where the problems hide: an underfunded reserve, rules that limit how you can use the unit, or an assessment that lands the month after you move in.
The Irrevocable Period, Explained
The irrevocable period is one of the most Ontario-specific parts of an offer, and it catches a lot of buyers off guard. Many assume they can pull their offer if the seller hasn't responded yet. They can't.
What it means legally
The irrevocable period is a date and time you write into your offer. It's the seller's deadline to accept. If they don't respond by then, the offer expires on its own.
The part most buyers don't realize: once you sign, you can't withdraw your offer before that deadline, even if you change your mind. Think it through before you sign.
If the seller counters instead of accepting, your original offer is off the table. You're free to accept their terms, counter back or walk away.
How long to set it
Irrevocable periods usually run from a few hours to 24 hours. When there's a set offer night, same-evening deadlines are common. A long window, three days or more in a busy market, gives other buyers time to come in with a bully offer and weakens your position.
How to Make Your Offer Stand Out
A complete offer gets you to the table. A well-built offer wins. In 2026, Milton sellers respond to buyers who price with data, structure their terms well and come prepared.
Tactics That Actually Move the Needle on Offer Night
- A larger deposit, delivered within 24 hours, shows commitment without raising your price.
- A closing date that suits the seller can be worth more to them than thousands of dollars in price.
- Short condition periods of 3 to 5 days, instead of 10, reduce the seller's uncertainty.
- A price based on recent comparable sales, not the list price, keeps you from overpaying out of fear.
Before you submit anything, ask the listing agent what matters most to the seller besides price. Knowing they need a specific closing date, or want to stay an extra month, lets you write an offer that wins on terms.
Why negotiation training matters
On a busy offer night in Milton, you may have hours to decide. When to try a bully offer, which conditions to shorten and which to keep, how to read what a seller really wants: that judgment comes from years at the table.
I hold the Master Certified Negotiation Expert (MCNE) designation, and I've lived in Milton for 23 years. I bring a structured negotiation plan to every offer, built on local sales data and what I learn about the seller. The difference between an accepted offer and a missed home often comes down to how it's put together.
Mistakes That Cost Buyers the Deal (and Sometimes the Deposit)
The most expensive offer mistakes are usually avoidable. They come from moving too fast, cutting the wrong corners or misreading how a clause works.
Waiving conditions without a plan
The two most common and costly errors I see: waiving the inspection without a pre-inspection, and waiving financing before your lender has approved that specific property. In a fast market, shorten your conditions instead of dropping them. A three-day inspection beats no inspection. A five-day financing condition with a pre-approval in hand is far safer than going firm on a guess.
Deposit, pricing and deadline errors
A late deposit, or one not paid in certified funds, can put your deal at risk and leave you in breach of contract. An irrevocable period that runs too long gives other buyers time to jump in. And pricing off the list price instead of recent sales leads to one of two outcomes: you overpay, or you send an offer the seller won't take seriously.
Putting Your Offer Together
Every part of your offer, the deposit, the conditions and the deadline, works together to protect you and help you win. When those pieces line up, the process feels clear. When they don't, it can cost you the home or put your money at risk.
The buyers who do best arrive ready: deposit lined up, conditions planned and a deadline set with the seller's needs in mind.
If you're getting ready to buy in Milton or anywhere in the West GTA, I'd love to help. I pick up the phone, explain every step in plain language and bring over a decade of offer-night experience to your purchase. Book a call with me or call or text 905-462-9801.
Still deciding on timing? Read Is Now a Good Time to Buy a Home in Milton?
FAQs About Making an Offer on a Home in Ontario
How legally binding is an offer once the seller signs?
Once the seller signs, you have a legally binding Agreement of Purchase and Sale, not a letter of intent. Most offers use OREA Form 100 (freehold) or Form 101 (condo), but a lawyer-drafted agreement is equally valid if it includes the required elements.
What must be included in an offer to buy a house in Ontario?
The purchase price, the legal land description, closing and possession dates, the deposit amount and due date, and a clear list of included fixtures and chattels. It should also list any rental items, such as a hot water tank or alarm system, and address HST in writing.
What's the difference between a firm offer and a conditional offer?
A firm offer has no conditions and is binding as soon as the seller signs. A conditional offer gives you a set window to confirm things like financing or an inspection. If a condition isn't met, you can walk away and get your deposit back. Firm offers are stronger in competitive markets, but waiving conditions without preparation puts you at risk.
How much deposit should I put down, and when is it due?
Usually 3% to 5% of the purchase price. On a $900,000 home, that's $27,000 to $45,000. It's generally due within 24 hours of acceptance, unless the offer says otherwise, and must be paid by bank draft or certified cheque. Personal cheques aren't accepted.
How should fixtures and chattels be listed?
List every item you expect to stay with the home, as specifically as you can. Also list any rental equipment or service contracts, so it's clear which obligations transfer to you at closing.
What is the irrevocable period on an offer?
It's the deadline you set for the seller to accept. You can't withdraw your offer before it expires. If the seller accepts in time, you have a binding agreement. If not, the offer simply lapses.
How can I make my offer more competitive without giving up protection?
Keep your conditions short and credible instead of removing them, and consider a larger deposit to show you're serious. An experienced local agent can also help you shape terms around what the seller needs, so you win without taking on risk you don't need.
Shaleni Henriquez, Sales Representative, Real Broker Ontario Ltd., Brokerage. Not intended to solicit buyers or sellers currently under contract.
Categories
Recent Posts